

Experian
Experian
- 4.7
- 196.87K Reviews
- 10.00M
- Downloads
- Free
- Price
Screenshots
Experian Pros and Cons
Pros
- User-friendly interface
- Comprehensive credit reports
- Alerts for credit changes
- Free basic services
- Improves financial literacy
Cons
- Premium features are costly
- Limited customer support
- Privacy concerns with data
- Complex cancellation process
- Occasional app glitches
 Analysis by All-app
I find Experian easiest to judge through a shared household situation: one person is planning a major purchase, while another is trying to make sense of a change in their credit report. The app can give each account holder a place to check their own credit information and learn how everyday financial choices may affect it. That can make a confusing topic feel more manageable, but it does not turn a personal finance account into a shared family dashboard. I’d treat it as an individual tool that can support household conversations, not as a way for one person to manage another adult’s finances.
One household, separate financial lives
Imagine you and your partner are reviewing the budget before applying for a loan. You could each use Experian to look at your own credit information, then compare notes about what needs attention. That’s more useful than passing one phone around and assuming a single view represents both people. Credit histories belong to individuals, so a shared plan still needs separate checks and honest discussion.
This distinction matters for roommates and other shared-device situations, too. If someone borrows your phone, I would not leave a financial app open or assume that a household device makes account access appropriate. Sign out or secure the phone when you are done, and keep account credentials private. The practical benefit is straightforward: people can coordinate around a goal without treating personal financial details as common household information.
Set expectations before you start
The app is free, which makes it approachable for someone who wants to explore credit monitoring without first committing to a paid finance service. Experian is the developer, and the app sits in the finance category. Its average rating is 4.7 from around 686,000 ratings, with more than 10 million installs, so it is clearly familiar to many users. Those figures may help establish that it is widely used, but they do not tell you whether its approach will fit your needs or whether you will enjoy using it.
I’d begin by deciding what you want the app to do for you: check credit information, understand possible score changes, or see whether eligible recurring payments might help build credit history. That keeps a first session focused. If you are setting it up while sitting with a partner or family member, let each person handle their own account and decide what, if anything, they want to share. A calm conversation about goals is more useful than exchanging passwords or trying to monitor each other.
The app is rated for Everyone, but that age label is not a reason to treat it as a children’s budgeting game. It concerns a serious subject, and a younger person may need an adult to explain what a credit score is and why it matters. I would keep any account setup and decisions about personal financial information with the person responsible for that account. The most constructive household use is educational: discuss general habits together while respecting each person’s private details.
Using Experian for everyday credit decisions
I’d use Experian as a prompt for better credit conversations, not as a household control panel. In the next section, I’ll look at how its alerts, simulator, and payment-related tools can help with ordinary decisions—and why checking the underlying details still matters before acting.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What the tools are useful for
Credit report alerts can be helpful when you want to notice changes rather than remember to check manually. A notification is a prompt to review what happened, not a complete explanation or a substitute for checking the underlying report. I’d use it as one part of a routine: open the alert, identify the change, and follow up through the relevant account or provider if something looks unfamiliar. That small workflow is more dependable than seeing a notification and assuming the issue has already been resolved.
The score simulator is best treated as a way to explore possibilities, not a forecast to plan a major decision around. I’d use it to ask “what might happen if…?” before taking an action, then remember that a simulation cannot guarantee the result a lender or another service will see. This is especially useful when you are weighing several choices and want a rough sense of their possible direction. It is less useful if you need a precise promise about a future score.
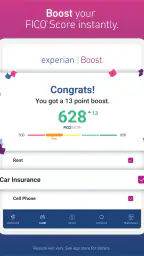
Experian Boost is another feature with a specific trade-off. Linking a bank account can allow eligible payments, such as utilities and streaming services, to be considered for credit, but I would not assume every bill qualifies or that the result will be identical for everyone. Before linking anything, consider whether the possible benefit is worth connecting an account, and review the terms and choices shown during setup. If you are uncomfortable linking a bank account, you can focus on the app’s other credit-information tools instead.
Where it fits beside other finance apps
Compared with a general budgeting app, Experian is more focused on credit information and credit-building options than on organizing a household’s entire spending plan. If your main challenge is tracking groceries, rent, and subscriptions across several people, a budget-first tool or a shared spreadsheet may be a better fit. If you mainly want a place to follow credit-related changes and learn how actions could affect a score, Experian’s narrower focus is an advantage rather than a gap.
It also serves a different purpose from checking information through a bank or card provider. Those tools may be convenient for monitoring one existing relationship, while a credit-focused app can give you a separate place to examine credit-related information. I would not rely on any single app as the only source for an important financial decision. Use the view that helps you understand the situation, then verify details with the relevant financial institution or report before acting.
Who will benefit—and who may prefer something else
I think the app is a sensible starting point for someone new to credit monitoring, someone who wants prompts when report details change, or someone curious about how certain choices could influence a score. The plain presentation can make it less intimidating than staring at unfamiliar financial terminology, and the simulator offers a way to explore decisions before making them. It can also help partners coordinate a financial goal, provided both people maintain separate accounts and share information voluntarily.
I would skip it, or at least avoid making it my main tool, if I wanted a complete shared household budget, detailed spending categories, or a system for controlling another person’s finances. It is also not the right choice for someone who wants a guaranteed score increase from a particular action. Credit outcomes depend on individual circumstances, so the useful mindset is to learn and monitor, not to expect a certain result.
For a practical routine, I’d check the app when a credit alert arrives, review the report change rather than reacting to the notification alone, and use the simulator before a decision that could affect credit. I would keep a separate note of questions to raise with a bank or lender instead of assuming the app can answer every account-specific issue. That approach makes the app a helpful checkpoint without letting it replace careful follow-up.
Getting to Know the Experian App
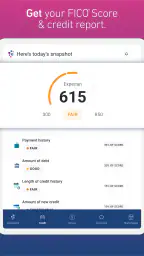
The Experian app is all about making your financial life a little less chaotic. Right off the bat, you'll notice how user-friendly the interface is. Let's be honest, nobody wants to spend hours figuring out how to navigate an app, especially when it comes to something as crucial as your financial health. With Experian, everything is laid out clearly, which makes it super easy to track your credit score, monitor your credit report, and even get personalized insights into your financial habits.
Features That Stand Out
One of the first things I noticed was the app's ability to provide real-time alerts about changes to your credit report. This is huge because staying on top of your credit is half the battle. I also loved the fact that Experian offers a credit score simulator. It's like having a crystal ball that lets you see how certain financial decisions might impact your score. Trust me, it's both fascinating and a bit terrifying.
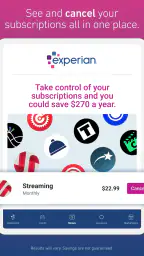
Another cool feature is the app's ability to help you enhance your credit score with Experian Boost. By linking your bank account, you can get credit for monthly payments like utilities and streaming services. Who knew Netflix and chill could actually help your credit score?
My Personal Take
Now, I know I sound like I'm fangirling hard, but the app genuinely surprised me with how much it offers. Sure, there are a ton of financial apps out there, but what sets Experian apart is its focus on empowering users with information. The app doesn't just show you numbers; it helps you understand them. Plus, with the added security features, like fingerprint login and identity theft protection, I feel like my data is safe and sound.
For someone like me who often feels overwhelmed by financial lingo, having an app that breaks everything down into bite-sized, digestible pieces is a game-changer. It's like having a financial advisor in your pocket, minus the hefty fees.
Wrapping It Up
If you're looking to take control of your financial health without drowning in spreadsheets and financial reports, then the app is definitely worth checking out. Whether you're trying to improve your credit score, keep tabs on your financial footprint, or just want to learn more about personal finance, this app has got your back.
The app is free and marked for Everyone, which may make it approachable for a broad range of users, though I’d still treat credit information as private and secure each person’s account separately. It was released on May 12, 2016, and its current version is 4.2.9, with Android support starting at version 7.0. Those details make it easier to judge whether it fits your device and household, but the real question is whether its credit-first approach matches what you need.
So, what are you waiting for? Dive into the world of Experian and start your journey towards better financial health. Who knows, you might just end up feeling like a financial guru yourself!
Frequently Asked Questions
What is Experian and how does it help users manage their credit?
Experian is a comprehensive credit management app that provides users with tools to monitor their credit scores, track financial activity, and receive personalized insights. The app helps users stay informed about their credit health by offering free credit reports, real-time alerts on changes to their credit profile, and tips to improve creditworthiness. It is an essential tool for anyone looking to manage and enhance their financial standing.
Is the Experian app safe to use for managing personal financial information?
Yes, the Experian app is designed with top-notch security features to protect your financial information. It uses advanced encryption methods to ensure that your data is safe and secure. Additionally, the app complies with all relevant privacy regulations, offering users peace of mind when managing their credit information. Regular updates are also provided to enhance security and address any potential vulnerabilities.
Can I access my credit score for free using the Experian app?
Absolutely, the Experian app allows users to access their credit score for free. Upon signing up, users receive free access to their Experian credit report and score, which is updated regularly. This feature helps users keep track of their credit health without incurring additional costs, making it a valuable tool for financial monitoring and planning.
How does Experian help in improving my credit score?
Experian offers various features aimed at helping users improve their credit scores. The app provides personalized tips and insights based on your credit profile, helping identify specific areas for improvement. It also offers a feature called Experian Boost, which allows users to add utility and telecom payments to their credit file, potentially increasing their credit score instantly. These tools work together to empower users in enhancing their credit health.
Does the Experian app offer any additional financial tools or services?
Yes, besides credit monitoring, the Experian app offers a range of additional financial tools and services. Users can explore personalized loan and credit card offers tailored to their credit profile, access identity theft protection services, and utilize budgeting tools. These features are designed to provide a holistic approach to financial management, ensuring users have the resources they need to make informed financial decisions.


